Showing posts with label savings. Show all posts

Tuesday, June 23, 2020

How Accountable To Your Wealth Are You?


"Only when the tide goes out do you discover who's been swimming naked."  - Warren Buffet

There has never been a better time to look at your finances then the present pandemic.


We've seen the market drop precipitously only to experience the best 50 day run in history.  Meanwhile, new unemployment numbers are in the millions and increasing each week.  The dichotomy of between what's happening on Wall Street and Main Street has arguably never been as stark as it is now. 


If you've been exposed in 2020 by a lack of liquidity (access to cash) and seen your overall net worth drop by greater than 15% in 30 day time frame, then now is the perfect time to rethink and reshape the foundation to your financial plan.  


There are critical elements this pandemic has exposed in the traditional financial model.  For the purpose of this article I'm going to focus on one area you probably give little thought to:


Your Savings Strategy


First...

What does your savings strategy look like?  


Do you save in a traditional bank?  Is your savings really an investment plan like a 401k?

These are important questions because whether you save your money in a bank or a government qualified retirement account, you've exposed your money to at least of 1 of the 3 main Wealth Destroyers that are eating away at your net worth.  

3 Wealth Destroyers


  1. Risk:  Can you lose money?
  2. Taxes:  How much of the growth do you keep?
  3. Inflation:  Are you staying ahead of the invisible tax that reduces your purchasing power?

(There's also a 4th Wealth Destroyer which I'll get to in a moment)

Second...

Does your savings strategy make you more accountable, more efficient, and more profitable?


Let me ask you in a different way so you can better understanding of what I mean.  


How much value do you place on cash? 


For most people, the value is very low.  


If you pay cash for large items, you likely don't save money on a planned schedule.  You simply save what's necessary for your next big purchase or emergency.  This is important because not having a systemized plan means you place very little value on your saved dollars.


Think of it this way, when you borrow money from a traditional bank, you pay interest.  If you save money, you expect to earn interest.  Yet, when you use your saved dollars, you don't put any value on that money but this is a HUGE MISTAKE because of the opportunity cost of paying with cash from your traditional accounts.


Remember, you either pay or earn interest.  Paying with cash means you give up the ability to earn interest on that cash forever, and this is true even if you are great at replenishing your savings account!

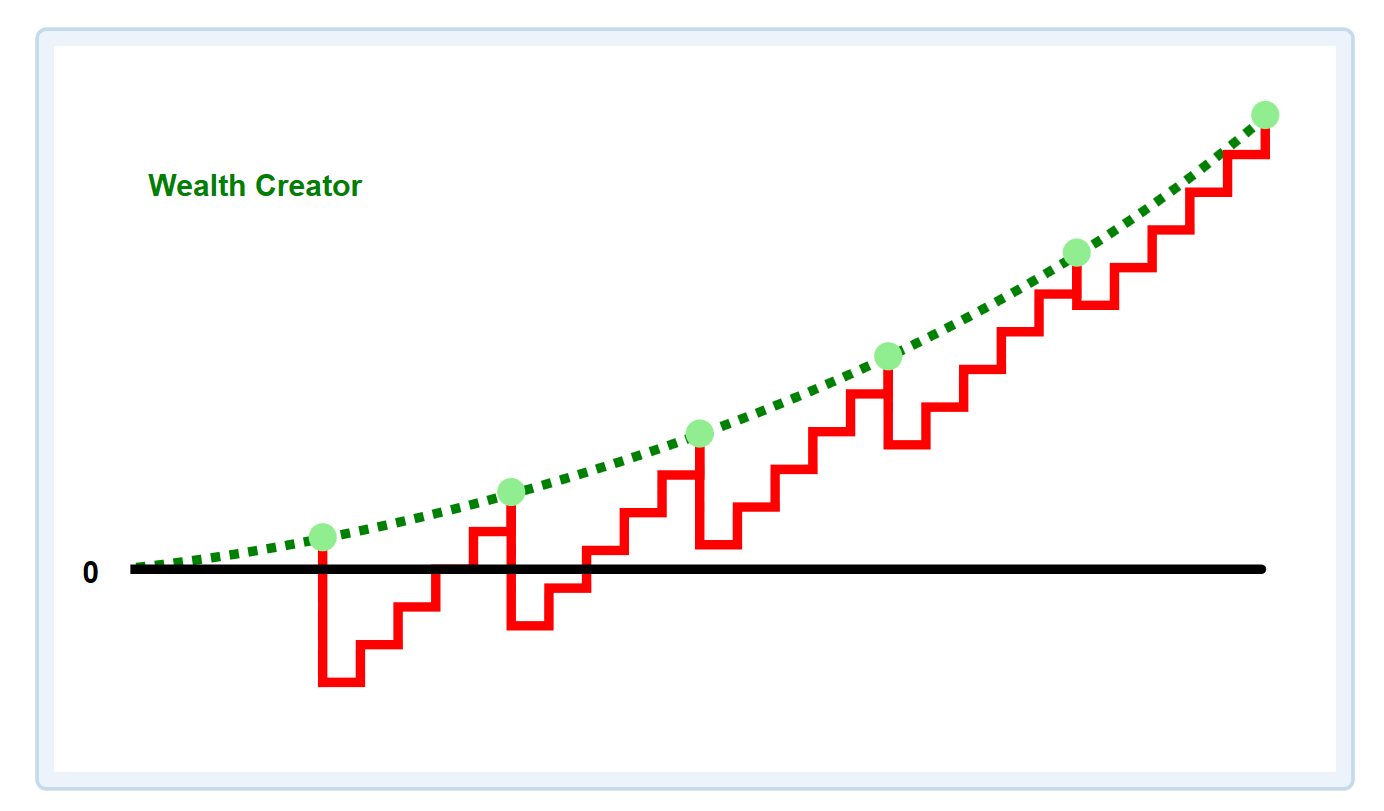
You save up, spend, and start all over.  Rinse, Repeat.  It looks like this:


Let's now plug a high early cash value (Infinite Banking) Whole Life policy into the equation and see how it holds up to the 3 previously mentioned Wealth Destroyers.  


  1. IBC Whole Life policies eliminate market risk,
  2. IBC Whole Life policies remove the taxes on the growth, use, and transfer of those dollars,
  3. Cash Values (and the future death benefit) are increasing at a pace that stays ahead of inflation,

and you have a Savings Strategy that incorporates an asset class that overcomes the 4th Wealth Destroyer:


The Constant Interruption of Growth


If you don't think this is important, ask yourself this:


How much money will pass through your checking/savings account in your lifetime never to be seen again? It's a large amount of money, am I right?!?  Wouldn't it make sense to allow that money to work for you all of your life rather than disappear forever?


When you use cash value to fund your lifestyle, pay for your kid's education, start or grow a business, or even prepare for retirement, you own an asset that you can use and re-use without interrupting the compounding curve of your saved dollars.


This is because cash values continue to grow on the full value even when there are loans taken.  You can't get uninterrupted growth with a traditonal bank account or 401k/IRA.


But to really make IBC work, you need to be accountable to your wealth!


A little discussed benefit to having an Infinite Banking Whole Life policy is how the use of this type of Savings Strategy makes you more accountable, efficient, and even more profitable than the traditional savings plan you currently use.  


People who don't understand how cash value life insurance works scoff at the notion of taking policy loans because they place little to no value on their saved dollars.  They don't know what they don't know...


Utilizing policy loans are critical to building your net worth because taking and repaying policy loans forces you to be accountable to your money, including when you use the cash values for investing.


On the point of using IBC for investing, my IBC Whole Life policies don't restrict me from making investments.  On the contrary, accessing the cash value via policy loans have made my investments more profitable by using leverage available in Whole Life policies to create two assets from the same dollar.


Here's the main point:


IBC forces you to replenish your wealth so that you never liquidate your savings without any intention of keeping it growing. 


If you are serious about accumulating wealth that can overcome all 4 Wealth Destroyers, it's imperative you evaluate your current savings strategy to be sure you setting the proper foundation for building wealth that can endure any financial storm.


And don't forget, just because a Whole Life policy is an unmanaged asset (it has guarantees and it can't lose money based on market whims), "practicing IBC" means you need to practice being accountable to the dollars you save!


Chances are you are already a good Saver.  You're just not saving in the best spot!


If you have questions about your current IBC plan or are looking to get started with IBC, you can connect with me here:  www.IBC.guru. 


Thank you,


John A. Montoya


Friday, June 17, 2011

How Much Does A Bank on Yourself® Policy Cost?

This is a great question. Most people are accustomed to buying term insurance because it is so cheap. It's great for that purpose but a term policy is all cost because it doesn't have any cash value growth.

Eventually only 2% of all term policies pay a death benefit. So 98% of the time, all the money paid into a term policy will be lost forever. This means your next generation will be no better off than you were during your life.

A permanent Whole Life policy structured as a Bank on Yourself® policy is designed as a savings account. It is contractually guaranteed to grow every single year!

I can show you how quickly the cash builds and the remarkable thing is how the cash value will pay for the cost of insurance which on this type of policy is guaranteed to never increase unlike with a universal life policy. Because a Bank on Yourself® policy is designed as a savings account and not like a life insurance policy, the question is not how much it costs.

The question is how much would you like to save on a monthly basis?


Call or email to request a free Bank on Yourself® analysis.


John Montoya
JLM Wealth Strategies, Inc.
john@JLMws.com
(925) 386-6639 Office
Authorized Advisor-Bank on Yourself®
CA Life#0C42222

Thursday, June 16, 2011

What Is Your Risk Management Plan For The Next Market Downturn?

Peter Schiff has said,"Within the next several years we are going to have the real economic crisis that we didn't have in 2008 ... Every time the government stimulates the economy to create an artificial boom to postpone the pain they make the inevitable bust that much worse."

With QE2 coming to an this month and QE3 becoming inevitable even if it's given a different name, the question is how long can a false recovery last? It could be a few years or maybe a decade or longer. There are no quick and painless solutions. Certainly we cannot expect the people responsible for creating the problem to be the ones responsible solving them.

The bigger question is: Who has the bigger problem: our government or us? When, not if, the economy collapses, will you have the correct risk management plan in place? Relying on our government to protect us is not option. The government will be too concerned about protecting itself and seizing more power from the people.

If you read this blog, I urge you to start taking steps to protect your savings. Here's an additional article written by Peter Schiff titled End Game. I encourage you to read it and watch the very short video below.

Call or email today to request a free report: (800)208-6141

John Montoya
JLM Wealth Strategies, Inc.
john@JLMws.com
(925) 386-6639 Office
Authorized Advisor-Bank on Yourself®
CA Life#0C42222

Friday, June 10, 2011

What's Going On In The United States These Days?

Glad you want to know. Click to read this article by Jim Willie at Financial Sense.

Mr. Willie provides an excellent summary of all you need to know about the financial chaos going on in our country. If you watch the evening news or read the newspaper on a regular basis, this is likely to be news to you (and real news at that). Stay informed. I encourage you to read alternative sources of news such as:

www.Mises.org
www.Lewrockwell.com
www.FEE.ORG
www.DailyReckoning.com
www.Sovereignman.com
www.Shadowstats.com
www.Elliottwave.com

If you think your bank is safe, think again.

Mr. Willie says that $7 trillion is sitting in FDIC insured bank accounts. If the government actually had that money, don't you think they would have found a way to spend it and replace it with IOUs by now?

The safest place you can have your cash is in a mutual whole life insurance policy. The money is backed by capital reserves that exceed the life insurance company's liabilities. In other words, these institutions are solvent! They are regulated to be this way.

Banks operate under the fractional reserve system meaning they keep a fraction of your deposit, lend the rest, and then inflate the money system by creating up to 10x the amount of your deposit in new money to lend out. In short, banks are highly leveraged and the main culprit in creating that nasty destroyer of wealth: inflation.

What about FDIC insurance? The FDIC inspires confidence. Just like Bernie Madoff did... and just like Bernie Madoff, the FDIC is insolvent.

Stick with what works.

A participating non-direct recognition whole life policy has been around for nearly 200 years. It'll be around for another 200+ years because it simply works. It is the safest place you can warehouse your cash.

Combine the fact that you can make $1 do the work of $2 by saving money with the same dollar being used to pay off debt, and you'll realize you're the smartest person in the room once you learn about the Bank on Yourself.

Despite all the uncertainty in the world today, one thing is certain. The business of banking is eternal and will survive what happens politically and economically in the decades to come. For that reason above all else, it's crucial that individuals have their own banking system. The sooner we, as individuals, control our flow of money through the creation of our personalized Infinite Banking system, the safer and wealthier we will become.

Go to www.CashValueBanking.com to learn more or call (800) 208-6141 to request a free analysis by a Bank on Yourself certified advisor. All appointments can be done over the phone and in front of your computer. Let your cash find a safe place before the storm clouds on the horizon gets any closer.

(Note: If you have a preconceived notion that this is like your mom's or grandma's whole life policy, you're sorely mistaken. A short online meeting can put that notion to rest quickly. And if you think you're too old or have health issues, we can look at insuring your spouse, child, or grandchild.)

John Montoya
JLM Wealth Strategies
(800) 208-6141

Monday, June 6, 2011

Add The 401k To The Long List Of Government Failures

We've all been taught that the way to save for retirement is through 401k/IRA government created qualified plans. I highly encourage you to change the way you think and do so while you'll still have time. Our government has a long history of failing when it attempts to create a solution to a problem. Nelson Nash, author of Becoming Your Own Banker, wants you to consider these monumental failures our government has cooked up for us:

  • The U.S. Postal Service was established in 1775. The government has had 236 years to get it right. It’s broke.
  • Social Security was established in 1935. The government has had 76 years to get it right. It’s broke.
  • Fannie Mae was established in 1938. The government has had 73 years to get it right. It’s broke.
  • The war on poverty started in 1964. The government has had 47 years to get it right. One trillion dollars of our money is confiscated each year and transferred to the poor, and they want more.
  • Medicare and Medicaid were established in 1965. The government has had 46 years to get it right. They’re broke.
  • Freddie Mac was established in 1970. The government has had 41 years to get it right. It’s broke.
  • The Department of Energy was created in 1977 to lessen our dependence on foreign oil. It’s ballooned to 16,000 employees with a budget of $24 billion a year, and we import more oil than ever before. The government has had 34 years to get it right. It’s an abysmal failure.
The government has failed in every service they’ve shoved down our throats while overspending our tax dollars. Now let’s see. You want to trust these folks with your plans for your retirement through tax qualified plans? Who has the problem here?

Insanity is doing the same thing over and over and expecting different results.
–Albert Einstein.

Just for fun, I'd like you to google: government retirement account. You'll find that our government is already plotting how to take over the retirement accounts it created to help us save for retirement. Our government knows they are going to need access to every dollar in these plans in order to buy our Treasuries (our country's debt) that no other country will be willing to touch in a few years time, if not sooner.

We are headed towards a Qualified Plan Disaster and you might not even be aware of it because the government and corporate propaganda machine has been running full steam ahead for years now. What's frightening is that people save for retirement using 401ks more so than any other type of savings vehicle. Are you starting to see the train wreck before it happens?

WHY DO WE FOLLOW THE CROWD WITHOUT QUESTION?

Challenge the traditional financial system of beliefs because they simply do not make any logical sense. Why save money in a retirement vehicle that exposes your money to both stock market loss and a lifetime of taxes when you retire? It's illogical. That's why I'm encouraging you to wake up now before it's too late.

For perspective, here's a quick story that I hope resonates.

It's about a woman who always cut off the turkey legs to roast a turkey. When asked by her daughter why she did it that way, the mom said because her mom did it that way and her mom's mom did it that way as well. It never occurred to her that grandmother's pan was too small to fit the entire turkey. Need I say more about questioning your belief system.

Go to my video at www.CashValueBanking.com to educate yourself on the best financial solution that exists to solve your retirement dilemma. Then call 800-208-6141 to schedule a free analysis from 1 of 200 authorized advisors nationwide with Bank on Yourself.

Sunday, May 29, 2011

The Simple Truth About Money

Understanding how Becoming Your Own Banker: The Infinite Banking Concept (IBC) works begins with understanding one very fundamentally important money principle. Some people will get it right away and for others it takes a bit longer, but what I've discovered over the years in my professional practice is that when you dedicate yourself to learning the truth about money and practicing IBC, you will ultimately have the IBC epiphany and be able to fully comprehend this one very simple truth about money:

You finance everything you buy.

You either lose the interest you could have earned or you agree to pay interest to someone else, most commonly your bank or finance company. It's as simple a principle as that. Flip a coin and you have two possible outcomes: heads or tails. It's the same scenario when you buy something. Give up interest earned as you pay cash or pay interest by financing it with a 3rd party. The interest you lose on your money adds up into the hundreds of thousands over one's lifetime. Is it any wonder why there are multiple banks on every major street corner in every town across the country looking for deposits? (As a side note, you should be asking yourself,"what is it that bankers know that I don't?)

Now it might seem to you either scenario, paying cash or financing, is a losing proposition. And it is a losing proposition for most of you just learning about Becoming Your Own Banker and not yet practicing it. However, it is a winning proposition for the owners of the banking system. Unfortunately, we've been taught to be customers of the banking system rather than owners of it.

Our lack of education about how the banking system works leaves us in a very vulnerable and powerless position. We are conscious about our ability to earn millions of dollars of income in our lifetime, but we're confused about where it all goes. This is because no one ever taught us how to harness our savings to re-deploy it over and over again within a banking system we own, control, and, therefore, profit from. For generations we have been ingrained to continually save money the way our family, friends, and neighbors do which means we've never investigated or been presented with an opportunity to own our banking system.

For this reason, the most prudent thing you can do is create your own banking system as written about in books such as Becoming Your Own Banker by R. Nelson Nash and Bank on Yourself by Pamela Yellen. In doing so, you'll eliminate the opportunity cost of paying cash or financing at your lenders terms. The interest you once squandered and principal of capital transferred will be re-directed back to your own banking system for a lifetime of use. Thus, you will be capitalizing on the things you'll buy in your lifetime instead of letting it slip through your hands and back to the bank.

As Nelson Nash is fond of saying,"You should receive two paychecks. One paycheck from what you do for a living and one paycheck from your banking system." He also says,"Businesses come and go, but the business of banking eternal." Since you are captive to your local bank, doesn't it make sense to be in the very business you use everyday?

If it sounds to good to be true, you're not alone in thinking so. This is only because, like most people, you haven't been presented with this knowledge before or, if you were like me, you failed to grasp the enormity of its power in creating risk-free, tax-free wealth for yourself now and your future generations the first time IBC was presented to you.

Before you continue on your journey learning about Becoming Your Own Banker, I'd like to recommend you open your mind to one simple truth: you finance everything you buy.

This blog, as well as my website at JLMWealthStrategies.com, is full of F.A.Q.s and articles relating to Becoming Your Own Banker: The Infinite Banking Concept. At this point, you can choose to ignore what you learn or you can heed this writers advice. I can tell you what the smart people I meet do with their personal and business money. They take control of it and having your own banking system gives you the ultimate power to do so.

For a free analysis, call (800) 208-6141.

John Montoya
John@JLMws.com
www.CashValueBanking.com

Monday, April 11, 2011

The Infinite Banking Concept (IBC)- The Most Frequently Asked Question

What's the most frequently asked question I get? Without hesitation:

Why haven't I heard about this before? It sounds too good to be true. 

There are many reasons.

First, this financial strategy seems to be given a new name every few years.  It is originally known as the Infinite Banking Concept (IBC).  Bank On Yourself is another popular name thanks to Pamela Yellen who's book by the same name hit multiple best-seller lists in 2009.  It's also been called Becoming Your Own Banker, Income For Life, the 770 Account, the Presidential Account, Private Reserve Strategy… you hopefully get the idea.  Many names for the same thing.

The Infinite Banking Concept/Bank On Yourself is a savings strategy (not an investment strategy) that also includes a death benefit.  This means Wall Street investment firms do not underwrite, market, or promote IBC/Bank On Yourself.

Sadly, the life insurance industry does not put much effort into promoting IBC/Bank On Yourself either.

Part of the reason is because IBC/Bank On Yourself policies strictly use only dividend paying Whole Life insurance policies.  There are only approximately 45 mutual life insurance companies left in the United States out of 1500+ that exist today.   Of those 45 or so mutual (owned by policyholders instead of shareholders as with a stock based company), maybe 10 offer a competitive and flexible Whole Life policy suitable to IBC/Bank On Yourself.

If you are wondering what the difference is between mutual and stock insurance companies, here's a brief explanation:

Any profits earned by a mutual insurance company are rebated to policyholders in the form of a dividend.  In contract, a stock insurance company is owned by investors who have purchased company stock.  Any profits generated by a stock insurance company are distributed to the investors without necessarily benefitting the policyholders.  This is why you want a dividend paying Whole Life policy from a mutual insurance company.


The savings component of a dividend paying Whole Life insurance policy is contractually guaranteed to increase in value every year and the life insurance company is on the hook for those increases regardless of economic conditions.  In comparison, Wall Street cannot offer any guarantees because they do not insure your money against losses.  They are paid to manage assets and you as the investor assume the risk of losses. The death benefit component of the IBC strategy can only be offered by life insurance companies.

Since Wall Street does not profit from the vehicle that best fits Becoming Your Own Banker, they have no incentive to sell it. Wall Street is primarily interested in 1) managing assets from which they can earn an annual management fee and 2) selling products that bear no financial risk to the firm when a clients assets fall in value.

As a better alternative to mutual funds and 401k's, it is Wall Street's worst nightmare come true should the public discover they could re-allocate their savings into accounts that are insured from loss, 100% access to their money without penalty, and provide tax-favored growth, distribution, and transfer including a life long death benefit protection. Think about it for a moment. Would you still choose a risky and tax-disadvantaged 401k for you and your family over what I just described?

Another reason why you may not have heard of Becoming Your Own Banker, while traditional banks can offer this specific type of life insurance product, doing so would eliminate the most profitable department of every bank: the lending department. Americans have been conditioned from one generation to the next to outsource their individual banking function to their traditional bank. These banks have no financial incentive to give their customers the ability to develop their own banking system within their larger banking system.

It wouldn't make any business sense for banks to teach and offer Becoming Your Own Banker because giving people the capacity to save and borrow from themselves would eliminate the need for banks as we know them. The only reason for having a traditional banking relationship would be limited to maintaining a checking account.

Ignorance is indeed bliss for bankers. Sadly, this is so true that not even bank employees know how to set up their own banking system. Ironically, the largest purchasers of cash value life insurance policies are banks.

Banks purchase more high cash value life insurance policies than any other institutions in the world! And they do it for a variety of reasons which any savvy individual would recognize are the same reasons they should be purchasing it for themselves: safety of principal, to enjoy tax benefits, strengthen financial stability, and to have contractually guaranteed growth provided by the most financially secured institutions in the world (life insurance companies).

Due to the volume of high cash value policies bought by banks, the policies they purchase are now known as Bank-Own Life Insurance or BOLI. Corporations do the same thing with policies known as Corporate Owned Life Insurance or COLI.

Also, the mainstream media is largely controlled by the same Wall Street financial institutions that pay for lobbyists to influence members of Congress. If you don't believe me, ask yourself how quickly Congress intervened to approve TARP money for troubled Wall Street investment firms and bank in 2008? It happened in days.

Compare this to how quickly these same elected officials were willing to reach an agreement on a fiscal budget to avoid a government shutdown. The budget shutdown didn't get resolved until the final minutes even though Congress had months to reach an agreement.

The point is Wall Street's advertising and lobbyist dollars have a direct influence on what we hear, read, and watch from our various news outlets. Turn on the evening news and before too long, you'll be updated on how the stock market fared. Tune into your favorite AM radio station for the same news.

Open any financial magazine, you'll find strategies created and recommended by Wall Street for the benefit of Wall Street. Sadly, we've been conditioned for far too long by the Wall Street marketing machine and now believe that the only option for saving money is investing with Wall Street.

You have to ask yourself why this is? Who benefits? Are there alternatives? If what you thought to be true wasn't, when would you like to know? Wall Street lost over 35% of your account values twice in the past decade. Do you really have to be convinced that any other strategy would be better?

Hopefully, you get the idea of why people haven't heard of Becoming Your Own Banker. There are many high power influencing forces (Wall Street, Traditional Banks, and the Corporate Media) that don't want you to know.

Now I'll get to the biggest culprit which may surprise you. Believe it or not, life insurance companies are as much to blame as any other entity previously listed. Life insurance companies offer an incredible product called dividend paying Whole Life insurance yet fail to invest the time and energy to properly train licensed agents how these policies are engineered to be the safest and most superior savings vehicle ever created.

The fact that whole life policies have survived over 150 years with little change should be testament enough to even the most skeptical of doubters. What is particularly interesting is that the sale of dividend paying Whole Life policies has seen a substantial increase in the last 10 years thanks to the many scandals and financial collapse of storied firms like Lehman Brothers and Bear Stearns and the demise of others who only survived by being swallowed by their peers (think Merrill Lynch and Morgan Stanley among others).

My hope is that the trend continues. I can't think of one person who would not benefit from having a safe, tax-free, and guaranteed way to grow their money.

As disappointed as I am in the life insurance industry for the lack of leadership in promoting the Infinite Banking Concept, I understand why life insurance companies choose not to invest the necessary time to train a licensed agent how to design and implement this strategy.

First and foremost, the failure rate for newly licensed agent is extremely high. The majority of new agents fail to make it past their first year. Secondly, any agent trained to sell a policy structured to meet the specific criteria of a Becoming Your Own Banker policy must be willing to take at minimum a 50% pay cut in commission. In some cases, the commission paid on a this type of policy is as great as a 70% cut in commission.

Since the life insurance industry, much like Wall Street advisors, is a sales driven industry, stomaching a 50-70% drop in pay for often what is 5 times the amount of work in educating prospective clients is simply too steep a price to pay.

From the perspective of a life insurance company and any business owner, does it make sense to train an employee who's likely to be doing something else in 12 months how to make 50-70% less on each case? It simply does not.

It's my belief that if insurance companies took the initiative to train a sales force on the Infinite Banking Concept, the length of a career agent would increase dramatically and it would also have the dramatic effect of strengthening the financial foundation of Americans who would benefit and prosper from having a rock solid financial foundation the Infinite Banking Concept provides and 401k/IRA/Mutual Funds simply cannot.


John A. Montoya
(925)386-6639
John@JLMws.com
JLM Wealth Strategies, Inc.
www.CashValueBanking.com