Showing posts with label life insurance. Show all posts

Friday, September 10, 2021

What's the Difference Between Guaranteed vs Non-Guaranteed Cash Values?


Guaranteed Vs. Non-Guaranteed:  Understanding Whole Life Values


I'm to going to discuss the difference between guaranteed vs non-guaranteed values within a Whole Life policy, why having a foundation of guarantees is arguably the most important detail in setting up a “family banking system”, and revisit what distinguishes a contract from an investment.


Guaranteed vs Non Guaranteed


Guaranteed Values:  this is the year by year performance guarantee in detail out to endowment (typically age 121).  It’s based on math and actuarial science.  Life insurance companies provide a blueprint based on worst case projections should a dividend never be paid during your lifetime.  Something to keep in mind:  All the life insurance companies we use for IBC have been around for at least 100 years, are A rated, and most importantly to me, they have never missed paying a dividend… ever!  So the guaranteed values reflect a scenario of no dividends for the life of the contract yet it’s a scenario that’s failed to material even for one year.  Let that sink in for a moment.


You essentially have a fool proof system that is guaranteed to increase in value without any luck, skill, or guesswork during your lifetime.  No other place for money exists with the same level of guarantees that what you want to have happen, will happen, even if you’re not around to see it.  The last part of course speaks to the tax-free death benefit bestowed on your beneficiaries when you graduate to the next level.


Non-guaranteed values:  Take the guaranteed values and now add non-guaranteed dividends from the surplus profit of a mutual based life insurance company.  That’s it.  Life insurance companies are highly profitable but legally they cannot guarantee the dividends they will pay out next year or, 5 years from now, or ever.  By law, they have to project future values based on the current dividend scale.  They can’t assume interest rates will increase in the future and project higher dividends.  So the non-guaranteed projections are IMO conservative estimates of future performance.


The most important detail in setting up a “family banking system”


For banking purposes, this is a one of a kind “turn-key”, ready made financial system that is created with the purchase of a Whole Life policy.  IBC practitioners who have been around will recall that Nelson Nash was fond of saying: “Every time a person buys a life insurance policy they are starting a business from scratch.”  That business of course is a private family banking business between you and the life insurance company at what Nelson would call the “you and me” level.  


Of course, you do have to read between the lines of the contract to fully grasp the idea of Infinite Banking.  This is where the majority of people who first stubble upon IBC get stuck in the weeds.  They see a life insurance policy and get stuck.


I once heard Nelson say that calling this financial system a Whole Life insurance policy is one of the worst things the life insurance industry has ever done.  Right from the start, the life insurance industry provided a label that continues to confuse the masses to this day.  The smallest minds see life insurance policy and that’s all it will ever will be.  


Those of you who take the time to read Nelson’s book “Becoming Your Own Banker”, listen to our 30+ episodes now all related to Infinite Banking, and speak to an Authorized IBC practitioner, will realize what Nelson said from the beginning.  The Infinite Banking Concept is an idea.  It is not about life insurance.  It’s about controlling the banking function at the you and me level to root out rent seeking traditional banking system that will have you believing their “lies, lies, lies”.  


And what is the biggest lie of all?


That you need Traditional banks to finance all the major capital expenditures in your lifetime.  Simply not true but this of course is not what we are taught.  12 years of government schooling, 100’s of higher education degrees, and none of it teaches you the history of money and the importance of banking?


Why?  It’s about control.  Control the flow of money, create debt, and traditional banks have a client for life.  It’s parasitic relationship that need not to exist.


To bring it back to Guaranteed Values, a whole life contract provides the legal framework for a financial entity that is guaranteed to increase in value every year of your life.  The contract also provides you with guaranteed access to the cash values.  You can never be turned away.  


Imagine the peace of mind knowing you have posited your labor into a system protected by contract law, is considered an asset available for your use with no questions asked, and it is only solely by you.  Nothing else in the financial world like it.  No 401k/IRA or asset class can replicate the guarantees of a Whole Life contract.


Contracts vs. Investments


We'll refer to this as "Contractual" Wealth vs “Statement” wealth.


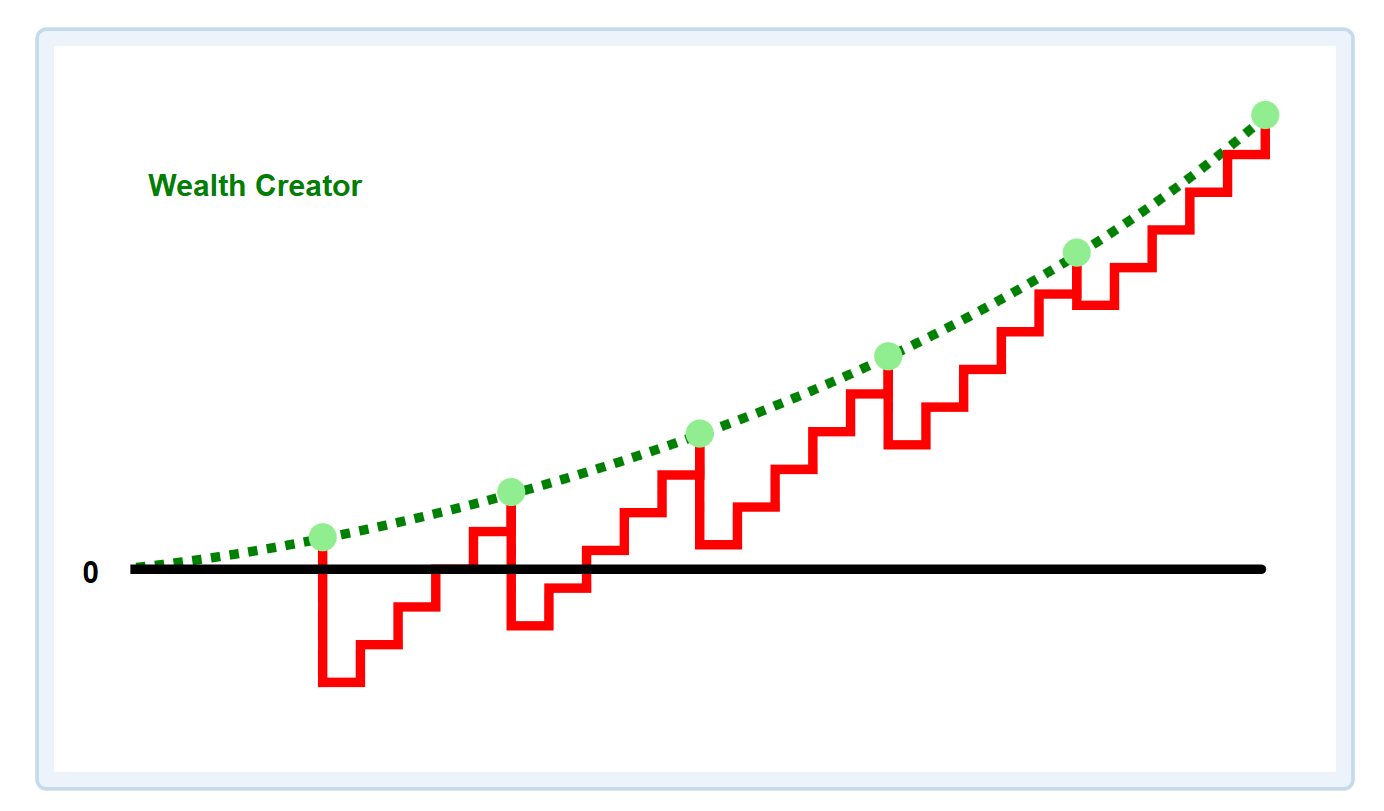
Statement wealth is when a client gives their money to an institution or organization in the hopes that they can get their money to grow. In this arrangement, the giver of the money assumes all the risk for the growth of the money. The organization sends a statement 1-4 times per year, telling them how they are doing at that time. 


Contractual wealth is when a client gives money to someone else as part of a contract. The recipient of the money assumes the risk.


Reminders:


IBC working is NOT predicated on dividend performance and chasing rate of return like you would with an investment.  It is a financial system, period. 


In order for a financial system to work, there must be a framework for money to move through it.  That’s what we are establishing with IBC Whole Life policies.  These contracts provide a framework for a financial system that allows you to control the flow of your money back to you where it can grow uninterrupted and so that we may continue to use that money repeatedly in our lifetime to build generational wealth.  


Think of it this way:  Instead of building beautiful fountains for the traditional banks, we can build our own.


If you have questions and would like to schedule a consultation with an Authorized Infinite Banking Practitioner, please visit the calendar here: www.IBC.guru


Thank you,


John Montoya


Saturday, October 17, 2020

4 Places For Money and Their Tax Consequences


In general, there are 4 places where money (assets) can be kept.  I'm going to leave out precious metals and cryptocurrency since the majority of people don't hold these assets, or if they do, it's an extremely small part of their net worth.


The most popular places people build wealth are:


Banks, Wall Street, Government (401k, IRA's), Life Insurance companies, and Real Estate so let's stick with these for the purposes of this discussion.


The 401k is under Uncle Sam’s control even when rolled over into an IRA.  Both are considered Qualified Retirement Accounts (QRP) --- that is, qualified with the government.  Rollovers (401k to IRA or IRA to IRA) don’t create a taxable event but eventually the government forces liquidations of these accounts thru Required Minimum Distributions at age 72.   


At the time of death, beneficiaries of 401k/IRA must withdraw all assets from an inherited IRA within 10 years following the death of the account holder according to the SECURE Act in December 2019.


Note: I  recommend looking at solutions that will help transition the account balance in an IRA rollover account to life insurance policies on your kids – or perhaps yourself if you might still be insurable - in order lower their future tax bill and also to create a multigenerational transfer of wealth.


Here's something to considering if you plan on doing a rollover from a 401k to an IRA (or IRA to IRA) to purchase an annuity:


With an annuity, the account balance equals the death benefit.  I mention this because the term death benefit in an annuity sometimes creates confusion for the public. Since an annuity is a contract with a life insurance company, the account balance upon on death is technically called a death benefit but there is no increase in the account value upon on passing like with a life insurance policy where cash values mushrooms and instantly becomes a much larger death benefit at the time of passing. (For example, a Whole Life policy pays a death benefit substantially larger than the cash value.)  


The life insurance death benefit does get included in your overall estate unless it’s in an Irrevocable Life Insurance Trust (ILIT) but the death benefit is income tax-free which makes it a superior distribution and transfer vehicle for beneficiaries.  A discussion on ILIT's will be important if your overall estate will in time exceed estate tax exemption.  In 2020, the estate tax exemption is $11.58 million for a single person.  Multiple this exemption by 2 for married couples.


Note:  If you've had a spouse that has passed, it's important for your advisor to know if you file IRS Form 706 at the time of his death to make an election to add his unused estate tax exemption to yours.


Let me know if this helps or if you have questions about your situation.  Here's my calendar to request a consultation:  www.IBC.guru


Thank you,


John Montoya


Tuesday, October 13, 2020

IBC Q&A Mailbag: The Power of Zero (Review)

The following is an email exchange with an existing client:


Hi John,


I have read the Power of Zero book by Dave McKnight, along with listening to many of his podcasts. I seem to resonate with his approach to matters. Have you read, and are you a fan of his approach to things also?


Thanks. 


My reply:

I am familiar the book and movie.  The director, Doug Orchard, actually produced and directed two of the videos on my website.   

(The 2 videos are at top of the page here: https://jlmwealthstrategies.com/videos/)


I like the Power of Zero strategy with regards to how it applies to indexed annuities.  I do have a difference of opinion as it applies to IUL’s because of the increasing cost of insurance within those policies.  I don’t believe the industry does a very good job of disclosing the risks with IUL’s.  The only mention of risk to a prospective buyer seems to be that money can’t be lost if the market goes down.  This is a half-truth at best.


There are actual risk esposures IUL's have but they are usually never mentioned.  The cost of insurance in an IUL increases every year by a larger amount which poses a major problem during retirement years.  IUL are sold on the idea that the returns will be there, and while it is possible they could be, but it’s also possible they won’t. Then what?


For this reason, I would only recommend an IUL for two sets of people:


1) High net worth clients who can commit a minimum $20k a year while still maintaining diversified portfolio of other assets AND life insurance policies. 

2) Parents living with diabetes who cannot otherwise qualify for a permanent cash value policy.  There is an IUL only program specifically designed for those with diabetes, currently unavailable with Whole Life.


Outside of these two demographics of people, I wouldn't recommend an IUL because I see too many buyers of IUL putting the majority of resources into one IUL plan and little elsewhere.  It’s a recipe for disaster because here's what I know as an experienced advisor what go wrong with an IUL:


Here are 5 Perils of an IUL


1.  The IUL cost of insurance is based on annual increasing one year renewable term.  Cheap when young, cost prohibitive once a person hits retirement.


2.  Returns could be below illustrated.  The increasing cost of insurance will only erode returns further. 


3.  Planned premium funding falls off because life happens.  Examples include layoffs, an extra kid (or two!), unplanned college expenses, failing health, divorce, lack of financial discipline... even pandemics!  Life does happen and failing to maximize the policy contributions of an IUL has an adverse effect on the returns of the policy because less premium means less cash value potentially earning interest to offset internal increasing costs of the life insurance.  


4.  IUL’s never endow.  


Only Whole Life policies can endow---- this means the cash value is guaranteed to equal the death benefit by age 121.  The current cash value in a Whole Life policy is actually the present value of the future death benefit.  This is hard to grasp at first but it’s very powerful.  


Essentially, a Whole Life policy is reverse-engineered from age 121 with fixed premiums and a minimum guaranteed growth rate completely uncorrelated to the market or economy.  What this means is that what you want to happen, will happen. A Whole Life policy provides a blueprint guaranteeing policy owners that their policies will eventually grow to equal the death benefit—even if their not around to see it.  


Furthermore, the PUA rider in an Infinite Banking designed Whole Life policies speed up the process by turbo-charging the cash values AND death benefit at no future cost.   In comparison, IUL is a side savings account based on positive market returns combined with the rising cost of a one year term policy.  While it’s nice IUL’s have the potential for 1-2% higher average returns than Whole Life, returns are dragged down by the rising cost of insurance over time, the unpredictability nature of market returns, and lack of discipline to stick to the planned premium when life events invariably happen.)


Underfunded and/or poor performing IUL policies should not be the foundational basis of a financial plan because IUL's have no guarantee of performance.  Just a guarantee of zero AND a guarantee of increasing life insurance costs.  As you can guess, I like building a financial plan with growth guaranteed each year and guaranteed fixed premiums that combined create financial certainties... hence Infinite Banking designed Whole Life.


5.  Taking income from an IUL during years of low and no return makes the cash value disappear even faster, especially so when the cost of insurance is rising exponentially after age 65.  It's the triple whammy that can't be avoided: no return, loans coming out, exponentially rising cost of insurance.  (This perfect storm of risk is even more pronounced in Variable Universal Life (VUL) policies).  


For this reason, I mention an IUL is not suituable for middle class income earners because they won't have a fallback plan if the majority of their eggs are in this one basket.  There’s just too many perils for middle class clientele to navigate to make it their main strategy.   


Unfortunately, there is an army of inexperienced life agents and advisors touting an IUL as the best thing since slice bread, and worse yet, people show me their IUL plans that have been designed the wrong way because there is too much death benefit (which means higher commissions for the advisor and an increased likelihood of that IUL to fall short of expectations).


All this said, The Power of Zero with Indexed Annuities is an excellent way to go because there is no life insurance mortality costs to eat away at the returns and many indexed annuities can be purchased with no annual fees or if choosing an indexed annuity for income purposes, a guaranteed lifetime income rider that averages 1% per year which is an extremely low cost for the peace of mind knowing you'll always have an income.


My thoughts are if people really want "The Power of Zero" without any true downside risk (no market risk AND no rising mortality costs), then combine IBC designed Whole Life policies with uncapped Indexed Annuities.  You get the best of both worlds (upside growth and the IBC banking strategy) without taking any unnecessary risk.


And one more thing, remember that if you're doing Infinite Banking right, you will have more than one IBC designed Whole Life policy. 


We can discuss further if you like by scheduling time on my calendar here:


www.IBC.guru


Thank you,


John Montoya


Tuesday, October 6, 2020

3 Things To Consider When You Delay Getting Started With IBC


It's possible you’ve been looking into Infinite Banking for a few months or even a few years now and perhaps you've yet to get started.  Sometimes the hardest thing is taking a leap of faith when doing something for the first time.  A few things to go consider:


  1. We don’t get any younger and our current health is never guaranteed.
  2. This is a guaranteed contract.  It’ll grow every year without any luck, skill, or guess work… and it gives you tax-free access to cash values via policy loans for any reason without interrupting the growth.
  3. If you have a family to protect, there is no better option for your “safe money”.


Check out my podcast if you’d like to continue to learn at your pace:  www.TheFifthEdition.com


Calendar:  I’ll be here when you are ready.  


Just keep in mind point #1 above and remember this:  


Time is the one thing we don't get back.  


Until this is taken care of, there are no guarantees except, of course, death and taxes. 


Cheers,


John


Tuesday, June 23, 2020

How Accountable To Your Wealth Are You?


"Only when the tide goes out do you discover who's been swimming naked."  - Warren Buffet

There has never been a better time to look at your finances then the present pandemic.


We've seen the market drop precipitously only to experience the best 50 day run in history.  Meanwhile, new unemployment numbers are in the millions and increasing each week.  The dichotomy of between what's happening on Wall Street and Main Street has arguably never been as stark as it is now. 


If you've been exposed in 2020 by a lack of liquidity (access to cash) and seen your overall net worth drop by greater than 15% in 30 day time frame, then now is the perfect time to rethink and reshape the foundation to your financial plan.  


There are critical elements this pandemic has exposed in the traditional financial model.  For the purpose of this article I'm going to focus on one area you probably give little thought to:


Your Savings Strategy


First...

What does your savings strategy look like?  


Do you save in a traditional bank?  Is your savings really an investment plan like a 401k?

These are important questions because whether you save your money in a bank or a government qualified retirement account, you've exposed your money to at least of 1 of the 3 main Wealth Destroyers that are eating away at your net worth.  

3 Wealth Destroyers


  1. Risk:  Can you lose money?
  2. Taxes:  How much of the growth do you keep?
  3. Inflation:  Are you staying ahead of the invisible tax that reduces your purchasing power?

(There's also a 4th Wealth Destroyer which I'll get to in a moment)

Second...

Does your savings strategy make you more accountable, more efficient, and more profitable?


Let me ask you in a different way so you can better understanding of what I mean.  


How much value do you place on cash? 


For most people, the value is very low.  


If you pay cash for large items, you likely don't save money on a planned schedule.  You simply save what's necessary for your next big purchase or emergency.  This is important because not having a systemized plan means you place very little value on your saved dollars.


Think of it this way, when you borrow money from a traditional bank, you pay interest.  If you save money, you expect to earn interest.  Yet, when you use your saved dollars, you don't put any value on that money but this is a HUGE MISTAKE because of the opportunity cost of paying with cash from your traditional accounts.


Remember, you either pay or earn interest.  Paying with cash means you give up the ability to earn interest on that cash forever, and this is true even if you are great at replenishing your savings account!

You save up, spend, and start all over.  Rinse, Repeat.  It looks like this:


Let's now plug a high early cash value (Infinite Banking) Whole Life policy into the equation and see how it holds up to the 3 previously mentioned Wealth Destroyers.  


  1. IBC Whole Life policies eliminate market risk,
  2. IBC Whole Life policies remove the taxes on the growth, use, and transfer of those dollars,
  3. Cash Values (and the future death benefit) are increasing at a pace that stays ahead of inflation,

and you have a Savings Strategy that incorporates an asset class that overcomes the 4th Wealth Destroyer:


The Constant Interruption of Growth


If you don't think this is important, ask yourself this:


How much money will pass through your checking/savings account in your lifetime never to be seen again? It's a large amount of money, am I right?!?  Wouldn't it make sense to allow that money to work for you all of your life rather than disappear forever?


When you use cash value to fund your lifestyle, pay for your kid's education, start or grow a business, or even prepare for retirement, you own an asset that you can use and re-use without interrupting the compounding curve of your saved dollars.


This is because cash values continue to grow on the full value even when there are loans taken.  You can't get uninterrupted growth with a traditonal bank account or 401k/IRA.


But to really make IBC work, you need to be accountable to your wealth!


A little discussed benefit to having an Infinite Banking Whole Life policy is how the use of this type of Savings Strategy makes you more accountable, efficient, and even more profitable than the traditional savings plan you currently use.  


People who don't understand how cash value life insurance works scoff at the notion of taking policy loans because they place little to no value on their saved dollars.  They don't know what they don't know...


Utilizing policy loans are critical to building your net worth because taking and repaying policy loans forces you to be accountable to your money, including when you use the cash values for investing.


On the point of using IBC for investing, my IBC Whole Life policies don't restrict me from making investments.  On the contrary, accessing the cash value via policy loans have made my investments more profitable by using leverage available in Whole Life policies to create two assets from the same dollar.


Here's the main point:


IBC forces you to replenish your wealth so that you never liquidate your savings without any intention of keeping it growing. 


If you are serious about accumulating wealth that can overcome all 4 Wealth Destroyers, it's imperative you evaluate your current savings strategy to be sure you setting the proper foundation for building wealth that can endure any financial storm.


And don't forget, just because a Whole Life policy is an unmanaged asset (it has guarantees and it can't lose money based on market whims), "practicing IBC" means you need to practice being accountable to the dollars you save!


Chances are you are already a good Saver.  You're just not saving in the best spot!


If you have questions about your current IBC plan or are looking to get started with IBC, you can connect with me here:  www.IBC.guru. 


Thank you,


John A. Montoya


Wednesday, May 20, 2020

IBC Mailbag: 3 Ways To Access Money from a Whole Life Policy

The following is an email reply to a new client requesting to access money for the first time.  This client emailed me requesting to "withdraw" money to pay off a car loan.


Hi ______,

So I’m going to be a bit of a nerd here because I want to be sure we are using the correct wording/terminology.

The best way to access funds is via policy loan because it doesn’t interrupt the compounding effect of the money in the policy and it is also a non-taxable event.

Withdrawing money physically removes your own money from the account and interrupts the compounding effect. 

I explain accessing money from a Whole Life policy this way to keep it simple:

There are 3 ways to access money


  1. The Sad Way
  2. The Dumb Way
  3. The Smart Way

The sad way is you pass away and the beneficiary gets the death benefit.  Let’s avoid that for as long as possible!

The dumb way interrupts compounding growth. 

The smart way, as mentioned, doesn’t interrupt the compounding growth of the cash values and is tax-free.


Utilizing the "Smart Way" allows you to be your banker.  You are essentially replacing the car finance company from the equation.  All the payments you would send to the car finance company will now be returned to your banking system (the whole life policy) where it will earn a guaranteed tax-free rate of return for the rest of your life!

All of this is possible by becoming your own banker through a dividend paying whole life insurance policy.  Why pay other financial institutions when you don’t have to?

So all that shared, it will take 3-5 business days upon request of the loan to see it in your checking account.  You’ll need to provide the insurance company with a voided check if they don’t have a checking account on record for you.  Also, I strongly recommend setting up a monthly draft for the policy loan repayment for at the least same amount you were sending the car finance company.  It's important to be an honest banker with our own money.  Please refer to the Grocery Store analogy in the Nelson Nash's book Becoming Your Own Banker.  I can help explain the analogy further if you like.


If I can assist with anything I’ve explained here, please let me know.  You can reach me here: www.IBC.guru.

Thank you,

John


Monday, April 6, 2020

Breaking Bad: One Decision That Could Have Saved Walter White from Becoming Heisenberg


So this coronavirus has given us all a chance to spend more time with our immediate family and, of course, binge even harder on our favorite TV shows.

I know I couldn't resist the opportunity to re-visit the downfall of Walter White and Jesse Pinkman on one of my all-time favorite shows: Breaking Bad.  I just finished watching the last episode of season 2 last night.  This show is about as perfect as a TV show can get.

There's just one thing that bothers me though.  Walter White never would have had to go all "Breaking Bad" into his alter ego Heisenberg if he had just done one simple and easy thing.

If you've watched the show, you know Walt is absolutely brilliant but his immense intellect and talents are relegated to teaching high school chemistry while all his peers have gone on to makes millions and/or earn industry accolades.  At one point, near the end of the show's run, his brother-in-law Hank calls Walt the dumbest, smartest person he's ever met.  That pretty much nails it for me, too.

You see, Walt had a choice up until he was diagnosed with lung cancer that could have altered his legacy for the good.  This one choice would have saved so many lives and heartache.  It wasn't just Walt's family that suffered from Walt's decision to build a meth empire.  There's Jane, Jesse's girlfriend, who choked on her own vomit as Walt watched her die and did nothing, the 167 passengers on flight 737 who also would still be alive, and this is just from the most recent episode I watched.  Talk about collateral damage.  The list of casualties can and does go on and on.

All of this happened for one reason.

Walt had one goal when he learned that he had advanced stage lung cancer.  He wanted to make enough money somehow so that his family would be taken care of after he was gone.  Financial security would be his legacy and gift to his family.

And he could have done it simply and legally.

Can you guess where I'm going with this?

This makes me think I need to get in touch with every teacher out to ask one specific question:

Do you have enough life insurance??? 


Seriously, that's all it would have taken for Walt to be at peace with his legacy and to save countless lives he irrevocably harmed.  

Of course, there would be no Breaking Bad to binge watch and enjoy.  Heck, the show would have been as boring as... the life insurance policy Walt would have owned on his life.

And if Walt had been overfunding a cash value life insurance policy like the Infinite Banking designed Whole Life plans I recommend for my clients, he could have had access to his cash values to pay for the best doctors and treatment without resorting to running behind his wife's back to cook meth in the desert with Jesse.

Most policies these days even have Accelerated Benefit Riders that give access to the death benefit while still alive.

The point I'm making is this, Walter White was definitely smarter than the average joe but when it came to protecting his family and leaving a legacy, he was as dumb as it gets.   

Please do yourself and your family a huge favor.

Lock in your insurability while you are still young and healthy with at least a convertible term policy.  This way you'll never have to... break bad.

If you need help determining how much life insurance you should own, contact me here:  www.IBC.guru.


Cheers,


John Montoya


Sunday, March 29, 2020

Infinite Banking for your Kids


How would you like to help prepare and secure your child’s financial future for all stages of their life including college and all the milestone that follow? 

Not ever having to worry about whether your child will be beholden to banks for massive student loans, crippling credit card debt, or any other type of bank debt?

Instead you could give your child the ultimate financial gift. 

Put them in driver’s seat so they can re-write the financial rules to escape the bank-controlled money system that plagues families from one generation to the next.

It’s the so-called “Rat Race” for a reason. 

But it doesn’t have to be your child’s financial destiny. 

The truth is our kids are destined to follow the same financial path we do. 

If you borrow money from a bank from one car purchase to the next, finance your home from mortgage to the next, contribute to a 401k plan praying the stock market can consistently perform so you can finally retire (March 2020 has seen the market crash 25% because of the Covid19 crisis!), I’m going to tell you something that deep down you probably already know. 


You’re saving money in the wrong place! 


Worse yet, your kids will adopt the same or similar money habits from you when they become adults.
Undoubtably, you're a proud parent who wants the best for your kids.  Why pass on a lifetime of financial insecurity?

The challenge Middle Class America has is not knowing what we can do differently for our kids instead of the traditional options… like bank savings accounts and 529 Accounts.  These savings options are mediocre at best.

The big question is: how can you give your child the best head start in life so they can avoid repeating the same financial blunders you've made?  Yes, you!  We all have to own our mistakes in life so let's keep it real.

What I’m going to share with you will help you give your child access to a tax-free reservoir of wealth they can use over and over and over again…at any point in life! 

Not only can it help pay for college but for ALL THE MILESTONES in their life. 

From buying their first car, their first home, start or buy a business, the opportunities they'll be able to take advantage of is unlimited.  That's the power of IBC.  It puts those who implement the strategy in the position to be "Master & Commander" (great movie by the way) of their financial ship!

And IBC will even be there to providing TAX-FREE income in retirement, too.

It’s been called “the Swiss Army Knife of Financial Planning” because of all its uses. 

I’ve even heard the Infinite Banking Concept® referred to as “the black box secret for the ultra-wealthy” because affluent families use it TO HAVE ACCESS to cash reserves WHENEVER NEEDED and FOR ANY PURPOSE.  Plus money kept in these accounts allow families to transfer wealth from one generation to the next.


It's the ultimate wealth building secret


And for kids, the power of time and uninterrupted compounding growth is the perfect recipe to help them navigate their entire financial life. 

I call it the “Junior Estate Builder” and this plan is so simple you’ll be surprised to learn it’s worked for over 150+ years secured by the safest financial industry in the world.

It’s where I put my kid’s savings because I know it will be there for every big event in their life and I invite you to do the same for your children.

In the next few minutes I’m going to share how you can give your child the best financial tool to navigate their life. 
  
This simple, proven financial strategy is so flexible it can be used for any purpose no questions asked. 

Imagine your child having a place to grow wealth without ever experiencing market losses and economic downturns, political uncertainty and social upheaval, or any global event that cut an asset in half without warning.  


With the Junior Estate Builder, every year is a good year


I know it sounds too good to be true but it does exist and it's even written into the IRS tax code.  It just happens to have the worse name ever which is why I choose to call it the "Junior Estate Builder".

With this strategy, your child will no longer be beholden to banks for loans.  No more worrying about getting dinged on their FICO scores, and having to verify income or employment will be a thing of the past.

I can tell you it’s such a peaceful existence to never having to deal with bank loans, high interest rates, and onerous fees. 

Then consider what your child will do for retirement.  401k plans were never meant to be the primary source for income in retirement.  They are fundamentally flawed plans.  Think about it.

Money in a 401k plan is tied up for decades.  Early access is penalized and taxed.  

The only option for growth comes with risky and complicated market-based options with many hidden fees.  In truth, these plans serve Wall Street and the government better than they will for your child. 

Wall Street locks in the revenue for decades with no performance guarantees in return, then the IRS takes a sizeable portion in taxes every year for life. 

Is this really a good plan?  Is it really the best you can do?

It only seems that way if it's all you know!

Well, most parents only know about 529 Accounts too, and like 401k plans, these are severely flawed as well.  

529 Accounts put money at risk like 401k plans, can be used for only college expenses, and once spent will never provide any additional value or benefit to your child... EVER!  

In short, 529 Accounts are a risky, single purpose strategy with no additional value past college. 

The greatest benefit to the Junior Estate Builder is how it can be used to help pay for college, but more importantly, it can be used as a private banking system to accumulate long-term wealth during your child's life.

Imagine a multi-use strategy where your kids can re-use the money over and over again to acquire assets like real estate, or start a business, or perhaps buy an existing business so they can be their own boss.

They can also use the money you save for them to finance all the cars they'll ever own, maybe even put their own kids (your grandkids!) thru college...

Ultimately, it will even provide tax-free income in retirement.

Remember when I mentioned that the Junior Estate Builder is the “Swiss Army Knife” of financial planning?  This is a versatile, flexible, and predictable money system unlike the traditional bank and Wall Street system that holds you captive with your own money.

The sad truth is that traditional financial planning amounts to life-long financial servitude to banks and Wall Street because those institutions control your largest assets.  Congress writes the laws and changes the rules all the time.

Does it make sense to be penalized for early access and eventually get taxed on every dollar withdrawn in 401k/IRA accounts?  These plans are designed more for our government's benefit (great source of annual revenue) and the average American accepts it blindly because “it’s what everybody does!”

And this bank/Wall Street monopolized money system keeps you from discovering the truth about this strategy which hides in plain sight waiting for you to discover it.

It's the secret traditional banks and Wall Street hope you never learn about.

And keeping you in the dark is the best way to ensure your child will learn the same money habits you have now which keep you and your kids tied to banks and Wall Street in perpuity.

This is the financial destiny your child will inherit from you but the strategy sessions I offer will help you and your child change the course of your financial future by getting your child started on a path that puts them in the financial driver’s seat during their lifetime.


As a parent I know you have the best intentions  


I have no doubt your intentions for your child are no different than my parents had for me.
They did what they thought was best for me as a child and most families still do something similar.

For me, it was one those passport savings account books that are now a relic of the past, especially with interest rates at 0% these days! 

Back when I was growing up interest rates were much higher than they are now, so it was pretty cool to see the money my savings account grow at 6-8% each year during the 80’s. 

My parents were dutiful savers and thankfully that discipline certainly rubbed off on me.

Problem is despite my parents work ethic and discipline to save as much as they could for me, they chose accounts that conditioned me at an early age to think of banks as trusted institutions.

The de facto place to always save money.  How was I to ever learn otherwise?  I have a feeling you can relate.

Unfortunately, I had no Rich Dad or wealthy uncle to help me learn about money.
 
For this reason I went to work in the financial services industry after college.  Fast forward 21 years and I’ve tried just about every financial vehicle that exists. 

And of the places I’ve put money, there has only been one strategy and asset class that has worked like clockwork each year.  

This strategy has given me access to money tax-free to deal with financial curve balls as well as financial opportunities (the ability to purchase multiple homes, rental properties, an apartment complex, precious metals, you name it), and do so without ever interrupting the foundational portion of my net worth.  


I stopped contributing after-tax money to mutual funds that left me susceptible to tax consequences each year, including years when I lost money in the market. 

No more maxing out my 401k’s/IRA’s where I was putting my money in financial prison for 3 to 4 decades. 

I even stopped directing money to my kids 529 Accounts.

The more I realized how beneficial this strategy was for me, the more I thought how I should be setting up my kids with the same strategy for when they come of age.

The traditional advice of using 529 Accounts just didn’t make much sense compared to the alternative I had discovered for myself back in 2007.

What really drove home the point for me was my experience as an advisor and seeing 529 College Savings Accounts take massive hits when the market corrected from 2007 to 2009.

It wasn’t just 401k retirement plans that suffered during the last big recession, kids with their 529 accounts, especially those about to go off to college suffered as well.  We are witnessing it now again with the Covid-19 pandemic.

My experience as an advisor also helped me learn the other downside to 529 Accounts which is that not every child goes on to college. 

Money in 529 accounts are taxed and penalized on the earnings if not used for educational purposes.  No such rules or restrictions on a Junior Estate Builder plan.

This was the icing on the cake for me.  No 529 Accounts.  Instead I would set my kids up what I now call the Junior Estate Builder.

I’d give my kids the freedom of choice and direction in life without ever being hamstrung by banks, Wall Street, or even Congress. 

The truth about money is this:


The only fix is taking matters into your hands  


You cannot continue to rely on banks, Wall Street and Congress created plans to create the future you desire.

You have to OWN AND CONTROL your future and you have to teach your kids how to OWN AND CONTROL their future as well.

The Junior Estate Builder gives you the ownership and control with your own “privatized banking system” and it's actually quite simple.

Through the use private dividend-paying Whole Life contracts structured for maximum cash values, I create and OWN the pool of money I use to finance my cars, homes, make investments, pay my taxes… and yes, even to supplement my future income in retirement TAX-FREE.   

All of it is accomplished without ever needing to finance (borrow money from a bank having to agree to their terms), relying on Wall Street roller coaster, or lock up money in lobster traps (401k/IRAs) Congress creates to capture tax revenue each year when I retire until the day I day.

Everything it does for me, it will also do for my kids who each have their own contracts.

Quite simply, the Junior Estate Builder will do for my kids more than any 529 Account could ever do AND do better than any 401k plan could do.

The freedom of this strategy is going to teach them how to be financially independent from banks and Wall Street so they can live the life they aspire to without the financial obstacles that handcuff Middle Class America.

Most importantly, with the power of compounding interest and youth, my kids and yours will have the benefit of time to make even small amounts today go an extraordinaryly long way tomorrow!

Each of my 3 kids have their own Junior Estate Builder.  It’s where I direct their savings and each year their accounts grow larger and larger, just like the adult versions I have for myself and my wife where between the two of us, we have 8 properly designed IBC® Whole Life contracts and counting.  Including my kids contracts, our family has 11 Infinite Banking designed Whole Life policies we direct money to each year.

Think of that for a moment.

Instead letting banks and Wall Street controlling our wealth, my family has total control of a growing pool of money every single year that we can use for any purpose.  

Two simple reasons why this works so well:

1. These are private placed contracts backed by mutually owned (shares are not traded publicly) life insurance institutions that have paid dividends for 150+ years consecutively, even thru the Great Depression. 

2.  These plans are an uncorrelated asset class meaning it has no connection whatsoever to the stock market so will never suffer a market drop.

In fact, unlike Wall Street,  these financial institutions put their own skin in the game by guaranteeing a minimum amount of growth each year no matter what happens in the economy. 

I have the ultimate peace of mind knowing the money I put away from my kids will always be there for them.

I especially love that my kids' financial plan is now all-inclusive for any direction they choose to go as adults. 

Imagine the financial freedom you could be giving your kids where they have the resources to own cars, buy a house, start or invest in a business without the need to ask a bank for financial assistance. 

Attending college is an important milestone but as a parent I really believe we need to look beyond transitioning our kids from high school to college. 

Let’s face it, these days it gets harder and harder to get ahead. 

One thing that often goes overlooked is that the better prepared our kids are to transition to adulthood, the less likely we will have to support them financially in their 20’s, even their 30’s.

You’ve probably heard college graduates are returning to live their parents more than ever these days.
Marriage, having kids, and buying their first homes are being delayed later and later these days.

The number one reason is because they don’t have the financial resources to step out on their own.   


And the results have been proven to work over and over and over again.

So you may be wondering, if this is so great, why haven’t I heard of the Junior Estate Builder?

Now in the financial services business you probably realize Wall Street and Banks will do anything to manage your money. 

They’ve monopolized  401k plans and 529 Accounts to the point all financial recommendations narrowly focus only on stock market-based portfolios. 

For Middle Class America, these are the choices talked about.

That’s the biggest reason why the Junior Estate Builder is the best financial secret hiding in plain sight.

It’s not a Bank and Wall Street created product or service.  Quite simply, they can’t, don’t, or won’t recommend it because it directs money outside of their control!  Remember, it's a very specific type of dividend-paying Whole Life policy.  Furthermore, it has to be structured just right to avoid becoming taxable later in life.

By now you should know when money is locked into 401k/IRA plans, that money becomes tied up for life! 

When the need for money arises, where must a family turn if they are prohibited from accessing their own the largest asset they own?

Middle Class America is forced to borrow money from banks, of course!  They refinance their home if possible or rack up sizeable credit card debt that will take years to pay off.

It’s a system designed with purpose to keep you on that Bank/Wall Street treadmill.

And unless you do something different for your kids, this treadmill is all your kids will likely ever know!

But it doesn’t have to be.

You now have a choice to take action.

You can take the next steps to help your kids avoid the same financial pitfalls.

I’ve made getting started so simple and easy for my clients, that way your kids don’t have to be another financial statistic who don’t have a rainy day fund or have enough to retire on when they are adults. 

The best part? 

You will know down to the dollar and year, how your child’s plan will perform, you will finally have the missing piece that moves your child’s financial life forward from one milestone to the next because they will have access to money tax-free when and where they need it. 


To setup the Junior Estate Builder system correctly, you must be able to do 3 things:


1.  You have to be able to think long-term.  This is not a get rich quick scheme.
Remember, saving for college is one milestone but your child will have many more milestones ahead of them.  Give them the resources to prosper at every stage of their life.

2.  You have to have the financial discipline to save money consistently.  $100 a month is the minimum.  If your budget allows for more, you can add more.

3.  Put the plan on auto-pilot.  It won’t require any luck, skill, or guesswork on your part to be successful because the contract is has guarantees, flexibility, and access to cash whenever it's needed.

If you can do these 3 simple things, you will ensure your child the ability to take advantage of any opportunity life presents them.

OR...you can continue doing what you’re currently doing for your kids hoping the plan works and in the case of 529 Accounts, hope it’s utilized for college. 

I have no doubt your kids will be grateful for any amount put away for their future. 

I know I was grateful for what my parents saved for me, but if you’re the type of parent that really wants to give your kids an edge financially, you owe it to your child to see how this plan can work for them.


Here is the next step to take:


Visit my calendar and request a strategy session here:  www.IBC.guru

Thank you,

John Montoya


Friday, February 28, 2020

Here’s Why You Should Only Work with an Infinite Banking Authorized Practitioner


When you need to prepare your taxes, you go to your tax professional.

When you set up your living trust, you go to an estate planning attorney.

When you want to buy or sell a property, you go to a real estate professional.

Foot issues?  See a podiatrist.  Is your baby is sick?  Go to a pediatrician.  Kitchen remodel?  Hire a contractor that specializes in kitchens.  And on and on we can go.


If this sounds like common sense, it’s because it is.  The point is we seek out specialists in their field when we have specific goals we want to accomplish.  It’s the best way to assure that we get what want-- the best advice from experienced professionals.


When it comes to the Infinite Banking strategy, there are specialists across the United States who have completed the necessary training and been approved by the Nelson Nash Institute to teach and implement the Infinite Banking strategy properly.  You can find an authorized practitioner here:  https://infinitebanking.org/finder/


Here is why you should only speak to an IBC Authorized Advisor:


Whole Life insurance is a financial product.  Infinite Banking is a financial strategy.


There’s no end to the amount of incomplete information about life insurance on the internet.  


There are many life insurance options and no one size fits all.  Anybody who tells you should only buy a certain type of life insurance product probably isn’t qualified to be giving advice in the first place or have a professional agenda to steer you to something only they can offer.


The best life insurance product is the one that accomplishes an individual’s goals and everybody’s situation and priorities are different.  If obtaining life insurance protection is your goal, you should work with a professional who can educate on the pro’s and con’s of all the different life insurance products available. 


Pretty simple.


Taking it a step further, if you are interested in learning more about Infinite Banking, it’s important to know Infinite Banking can be accomplished with different financial products but none as well as a participating Whole Life policy from a mutual life insurance company. 


Definition of product:  an article or substance that is manufactured or refined for sale.
Definition of strategy:  a plan of action or policy designed to achieve a major or overall aim.


If you want to incorporate Infinite Banking into your personal financial picture, then you want a strategy, not a product.  To that end, you want a specialist who knows the field better than the rest.


In working with an IBC authorized practitioner, you’ll be working with someone who practices the strategy and can speak about their personal experiences.  They should be able to tell you exactly how they’ve used the strategy to build wealth.  If they can’t do that, they have not fully implemented IBC. 


Furthermore, any advisor can speak about a Whole Life policy but most advisors don’t even own a Whole Life policy let alone practice Infinite Banking.  Owning and practicing Infinite Banking with a properly designed IBC Whole Life policy is a world of difference!


In addition to the specific Infinite Banking training they receive, all IBC authorized advisors must own their IBC designed policies in order to be certified practitioners by the Nelson Nash Institute. 

   
It’s worth mentioning that not all Whole Life policies are the same and certainly not up to the criteria needed to be used for Infinite Banking.


Example, people who buy final expense whole life policies technically have a whole life policy but this is far different policy from the type of whole life policy an IBC authorized advisor would use for Infinite Banking.  Final expenses have little to no cash value growth and no flexibility or collateral capacity to use for banking purposes.


Another example are Gerber baby policies.  These are technically Whole Life policies but they are non-participating policies which means they pay no dividends.  They also cannot be used for banking purposes. 


Switching gears, it pains me to say that there are advisors who advocate and teach Infinite Banking but are not Infinite Banking authorized advisors.  They have not been interviewed by the Nelson Nash Institute, passed the necessary curriculum and gone thru the mentoring program to be approved as an IBC authorized advisor.   They contribute nothing to the community of advisors who have committed to upholding the highest levels of integrity to the public who are asking for the Infinite Banking strategy.


All IBC authorized advisors take very seriously a code of ethics to structure and implement only the correct type of Whole Life policies for the Infinite Banking strategy.  It’s because advisors were using the Infinite Banking name and peddling different recommendations that Nelson Nash created what was first called the Infinite Banking Institute, later changed to the Nelson Nash Institute by the board of directors to honor Nelson and his legacy.


My advice:  work with an IBC authorized advisor who is trained and vetted versus those who fail to meet the requirements and can potentially put you at risk by recommending policies that are not right for the IBC strategy. 


If an advisor is promoting IBC but is not a verified advisor on the Nelson Nash Institute website, you should ask him/her why that is.   


Action Plan:  3 Steps

1.      Connect with an IBC authorized advisor.  Get a high level overview and learn the basics of the strategy.  If it makes sense logically, request a customized plan.

2.      Complete a financial analysis with your IBC authorized advisor.

3.      Schedule an online or in-person appointment to review your IBC recommendations.  If the plan makes sense for you, start the underwriting process to implement. 


JLM Wealth Strategies, Inc.
IBC® Authorized Practitioner
CA Life#0C42222
  SealVert_DIscnFlame-1