Tuesday, September 22, 2020

Infinite Banking IUL

 If there ever were two things that don't go together it's "Infinite Banking" and "IUL".


I try to avoid Facebook like a plague but every now and then I do log in.  There are just too many ads and rants for my liking.  One of first ads I saw was for, you probably guessed it, "Infinite Banking IUL".


If you should see one of these ads, videos, or blogs posts from anyone touting the benefits of Infinite Banking, run in the other direction.


The Nelson Nash Institute is the only place on the internet where you can find an Infinite Banking Authorized Practitioner.  Here's the link:  


https://infinitebanking.org/finder/


One of the reasons the Nelson Nash Institute was created was to root out the imposters posing as Infinite Banking experts.  This was largely because advisors were liberally taking the Infinite Banking strategy and then selling IUL's (Indexed Universal Life insurance).


Only Dividend Paying Whole Life policies are to be used for Infinite Banking.  The reasons are multiple but the main one is that a Whole Life policy when structured for Infinite Banking avoids unnecessary risks embedded into the flawed design of an IUL policy that poses long-term risks on the performance of these policies.


No such performance risks exist with a Whole Life policy because the premium on a Whole Life is fixed from day 1 and there are no surrender penalties.  Cash values are readily available to be used as soon as 30 days.  IUL's doesn't have the same set up.  


And this is just the tip of the iceberg.  If you are being quoted an IUL, let me know.  I can walk you through the in's and out's of an IUL and show you what a true Infinite Banking plan looks like.


You'll find me here: 


www.IBC.guru


Thank you,


John Montoya


Friday, September 11, 2020

Discussing Financial Milestones as a Parent


Discussing Financial Milestones as a Parent

Thursday, July 30, 2020

IBC: Planning For Your First (or Next) IBC Policy AKA "The Future Planning Strategy"


Sometimes it's not possible to get started with an Infinite Banking designed Whole Life policy right away.

One of the primary reasons is due to cash flow restraints. In this scenario, the best alternative is securing a convertible term policy.

If you can budget $20-50 a month, you could lock in a 10 year term policy now that can be used to convert to an IBC designed Whole Life within the next 10 years.  

(Your age, health rating, and amount of death benefit will ultimately determine your monthly premium)

From experience, including my own term policies, I can share the majority of my clients convert their term policies within 5 years to an IBC Whole Life policy.

Life insurance companies will often also provide a credit for the previous 12 months of premium when the term policy is converted. 

Plus, if you are married and/or have kids, the death benefit from the term policy gives your family added protection. 

If you are single, then the convertible term policy is merely to guarantee your health so that you qualify for the IBC Whole Life policy when ready. It's like buying a stock option in that regard where the stock option gives the person the right to buy shares of a company within a specified timeframe. In this case, the convertible term is the " Whole Life option".

I'm a lifer to the insurance business. My first official job after college was with John Hancock Financial. Since that time  I’ve seen a number of people wait to get a policy for various reasons only to lose their health (prostate cancer, stroke, diabetes, complications from a car accident, etc.). I’ve seen a lot of bad luck happen to good people. 

For that reason, I try my best to get people, at a minimum, considering a convertible 10 year term policy.

This type of pre-IBC planning is what I refer to as "Future Planning".  It also works great if you already have one or more IBC Whole Life policies.

I keep a 10 year term policy despite owning multiple IBC designed Whole Life policies.  I keep it available so I know with 100% certainty I can open my next IBC policy even if my health changes for the worse.

Let's face it. This pandemic has proven once again that anything that can happen, will happen!

Back to my own term policy... when I eventually convert my existing term policy to my next Whole Life policy, I'll also look to obtain another 10 year term policy so I can repeat the same process for the next 10 year window of my life.  

If you would like to learn more about getting yourself set up for your first or next IBC plan AKA doing some "Future Planning", let me know.  You can find me here:  www.IBC.com

Thank you,


John Montoya


Sunday, July 12, 2020

Are You Thinking About Retiring Early?


Life doesn’t always go as planned, and if you’re currently navigating a new set of circumstances that has led you to consider an earlier retirement, it’s important to proceed carefully and thoughtfully.

Is it possible for you to retire early? If so, what’s the best way to go about it?
To start, take a look at these basic considerations and reach out if you’d like to check in.

Strategize Social Security

You may be able to start collecting Social Security at age 62, but many people choose to hold off if they’re able to. Waiting until your full retirement age (which depends on your birth year) or up until age 70 will lead to an increase in benefits.

Rebalance as Needed

Whether it’s by re-examining your portfolio or shifting more assets to cash (or both), try to make sure you’re finding the right balance and reducing risk as needed.  

One of the best ways to reduce risk is to consider an indexed annuity as part of your overall portfolio.

Indexed annuities do 2 things extremely well:

  1. Principle protection with upside growth
  2. Offer guaranteed lifetime income streams


Create a Withdrawal Approach

While many retirees aim to withdraw around 4% of their investments in the first year of retirement and adjust the amount for inflation going forward, there are no set rules for success. 

In fact, most fiancial pundits are now saying because of market volatility you should withdraw no more than 3% per year in retirement to avoid running out of money.  You may decide to withdraw more or less depending on your budgeting habits and age. 

To see where you stand now, multiply your current savings by 4% and divide by 12 to find what your monthly income amount would be.

If you are needing a withdrawal rate greater than 4% to ensure you won't run out of money in retirement, this is another reason to consider an annuity which typically have withdrawal rates greater than 4%. 

Other Factors

Don’t forget about additional considerations like health care and taxes. Overall, it’s important to sit down and calculate your anticipated monthly expenses (including a cushion for anything unexpected).

Do you need assistance mapping out your short-term, mid-term and long-term goals? It's extremely important that you make sure your guaranteed income in retirement covers all expenses.  Reach out anytime to discuss your questions here:  www.IBC.guru


Thank you,


John Montoya


Tuesday, June 23, 2020

How Accountable To Your Wealth Are You?


"Only when the tide goes out do you discover who's been swimming naked."  - Warren Buffet

There has never been a better time to look at your finances then the present pandemic.


We've seen the market drop precipitously only to experience the best 50 day run in history.  Meanwhile, new unemployment numbers are in the millions and increasing each week.  The dichotomy of between what's happening on Wall Street and Main Street has arguably never been as stark as it is now. 


If you've been exposed in 2020 by a lack of liquidity (access to cash) and seen your overall net worth drop by greater than 15% in 30 day time frame, then now is the perfect time to rethink and reshape the foundation to your financial plan.  


There are critical elements this pandemic has exposed in the traditional financial model.  For the purpose of this article I'm going to focus on one area you probably give little thought to:


Your Savings Strategy


First...

What does your savings strategy look like?  


Do you save in a traditional bank?  Is your savings really an investment plan like a 401k?

These are important questions because whether you save your money in a bank or a government qualified retirement account, you've exposed your money to at least of 1 of the 3 main Wealth Destroyers that are eating away at your net worth.  

3 Wealth Destroyers


  1. Risk:  Can you lose money?
  2. Taxes:  How much of the growth do you keep?
  3. Inflation:  Are you staying ahead of the invisible tax that reduces your purchasing power?

(There's also a 4th Wealth Destroyer which I'll get to in a moment)

Second...

Does your savings strategy make you more accountable, more efficient, and more profitable?


Let me ask you in a different way so you can better understanding of what I mean.  


How much value do you place on cash? 


For most people, the value is very low.  


If you pay cash for large items, you likely don't save money on a planned schedule.  You simply save what's necessary for your next big purchase or emergency.  This is important because not having a systemized plan means you place very little value on your saved dollars.


Think of it this way, when you borrow money from a traditional bank, you pay interest.  If you save money, you expect to earn interest.  Yet, when you use your saved dollars, you don't put any value on that money but this is a HUGE MISTAKE because of the opportunity cost of paying with cash from your traditional accounts.


Remember, you either pay or earn interest.  Paying with cash means you give up the ability to earn interest on that cash forever, and this is true even if you are great at replenishing your savings account!

You save up, spend, and start all over.  Rinse, Repeat.  It looks like this:


Let's now plug a high early cash value (Infinite Banking) Whole Life policy into the equation and see how it holds up to the 3 previously mentioned Wealth Destroyers.  


  1. IBC Whole Life policies eliminate market risk,
  2. IBC Whole Life policies remove the taxes on the growth, use, and transfer of those dollars,
  3. Cash Values (and the future death benefit) are increasing at a pace that stays ahead of inflation,

and you have a Savings Strategy that incorporates an asset class that overcomes the 4th Wealth Destroyer:


The Constant Interruption of Growth


If you don't think this is important, ask yourself this:


How much money will pass through your checking/savings account in your lifetime never to be seen again? It's a large amount of money, am I right?!?  Wouldn't it make sense to allow that money to work for you all of your life rather than disappear forever?


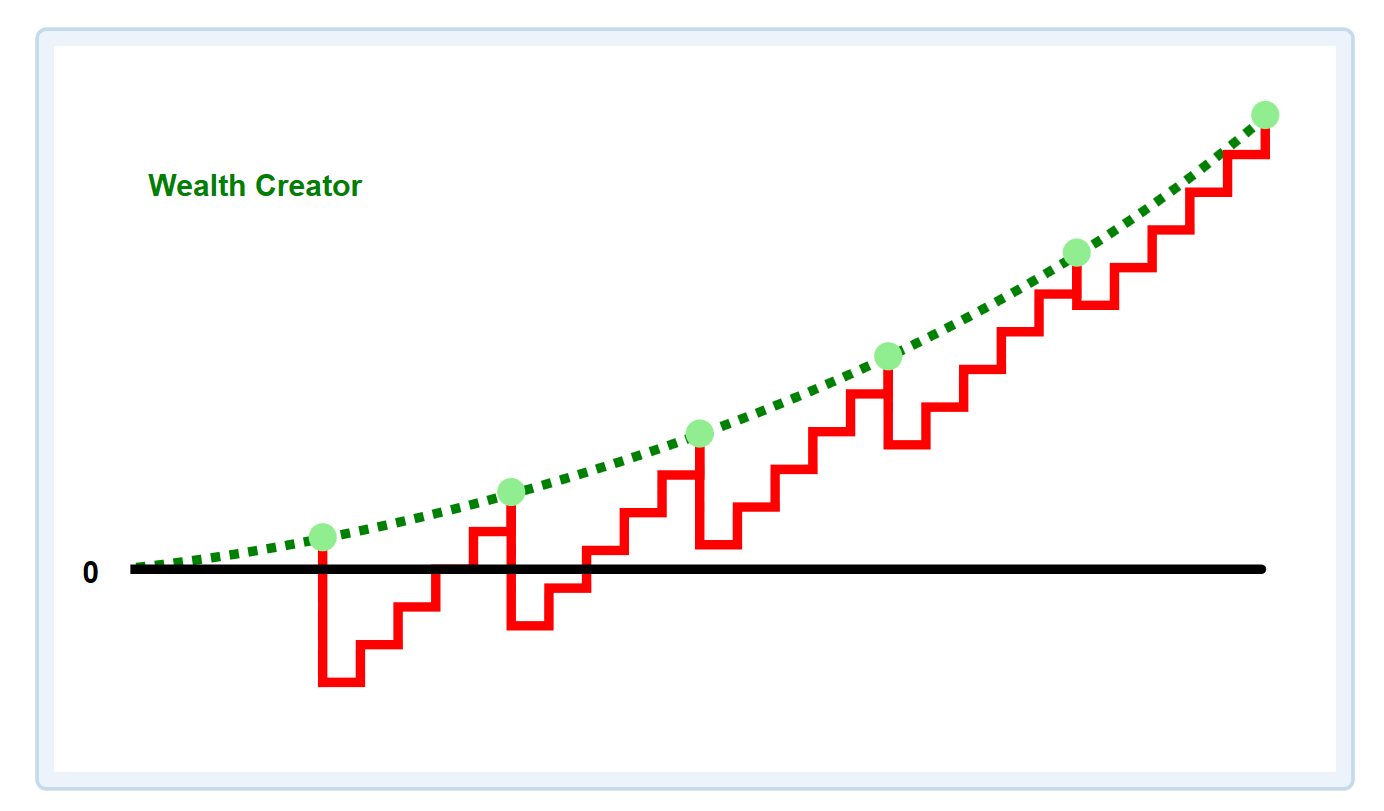
When you use cash value to fund your lifestyle, pay for your kid's education, start or grow a business, or even prepare for retirement, you own an asset that you can use and re-use without interrupting the compounding curve of your saved dollars.


This is because cash values continue to grow on the full value even when there are loans taken.  You can't get uninterrupted growth with a traditonal bank account or 401k/IRA.


But to really make IBC work, you need to be accountable to your wealth!


A little discussed benefit to having an Infinite Banking Whole Life policy is how the use of this type of Savings Strategy makes you more accountable, efficient, and even more profitable than the traditional savings plan you currently use.  


People who don't understand how cash value life insurance works scoff at the notion of taking policy loans because they place little to no value on their saved dollars.  They don't know what they don't know...


Utilizing policy loans are critical to building your net worth because taking and repaying policy loans forces you to be accountable to your money, including when you use the cash values for investing.


On the point of using IBC for investing, my IBC Whole Life policies don't restrict me from making investments.  On the contrary, accessing the cash value via policy loans have made my investments more profitable by using leverage available in Whole Life policies to create two assets from the same dollar.


Here's the main point:


IBC forces you to replenish your wealth so that you never liquidate your savings without any intention of keeping it growing. 


If you are serious about accumulating wealth that can overcome all 4 Wealth Destroyers, it's imperative you evaluate your current savings strategy to be sure you setting the proper foundation for building wealth that can endure any financial storm.


And don't forget, just because a Whole Life policy is an unmanaged asset (it has guarantees and it can't lose money based on market whims), "practicing IBC" means you need to practice being accountable to the dollars you save!


Chances are you are already a good Saver.  You're just not saving in the best spot!


If you have questions about your current IBC plan or are looking to get started with IBC, you can connect with me here:  www.IBC.guru. 


Thank you,


John A. Montoya